Gambling MCC Code 7995: Rules, Costs & Approvals

Discover the future of payments
Table of Contents

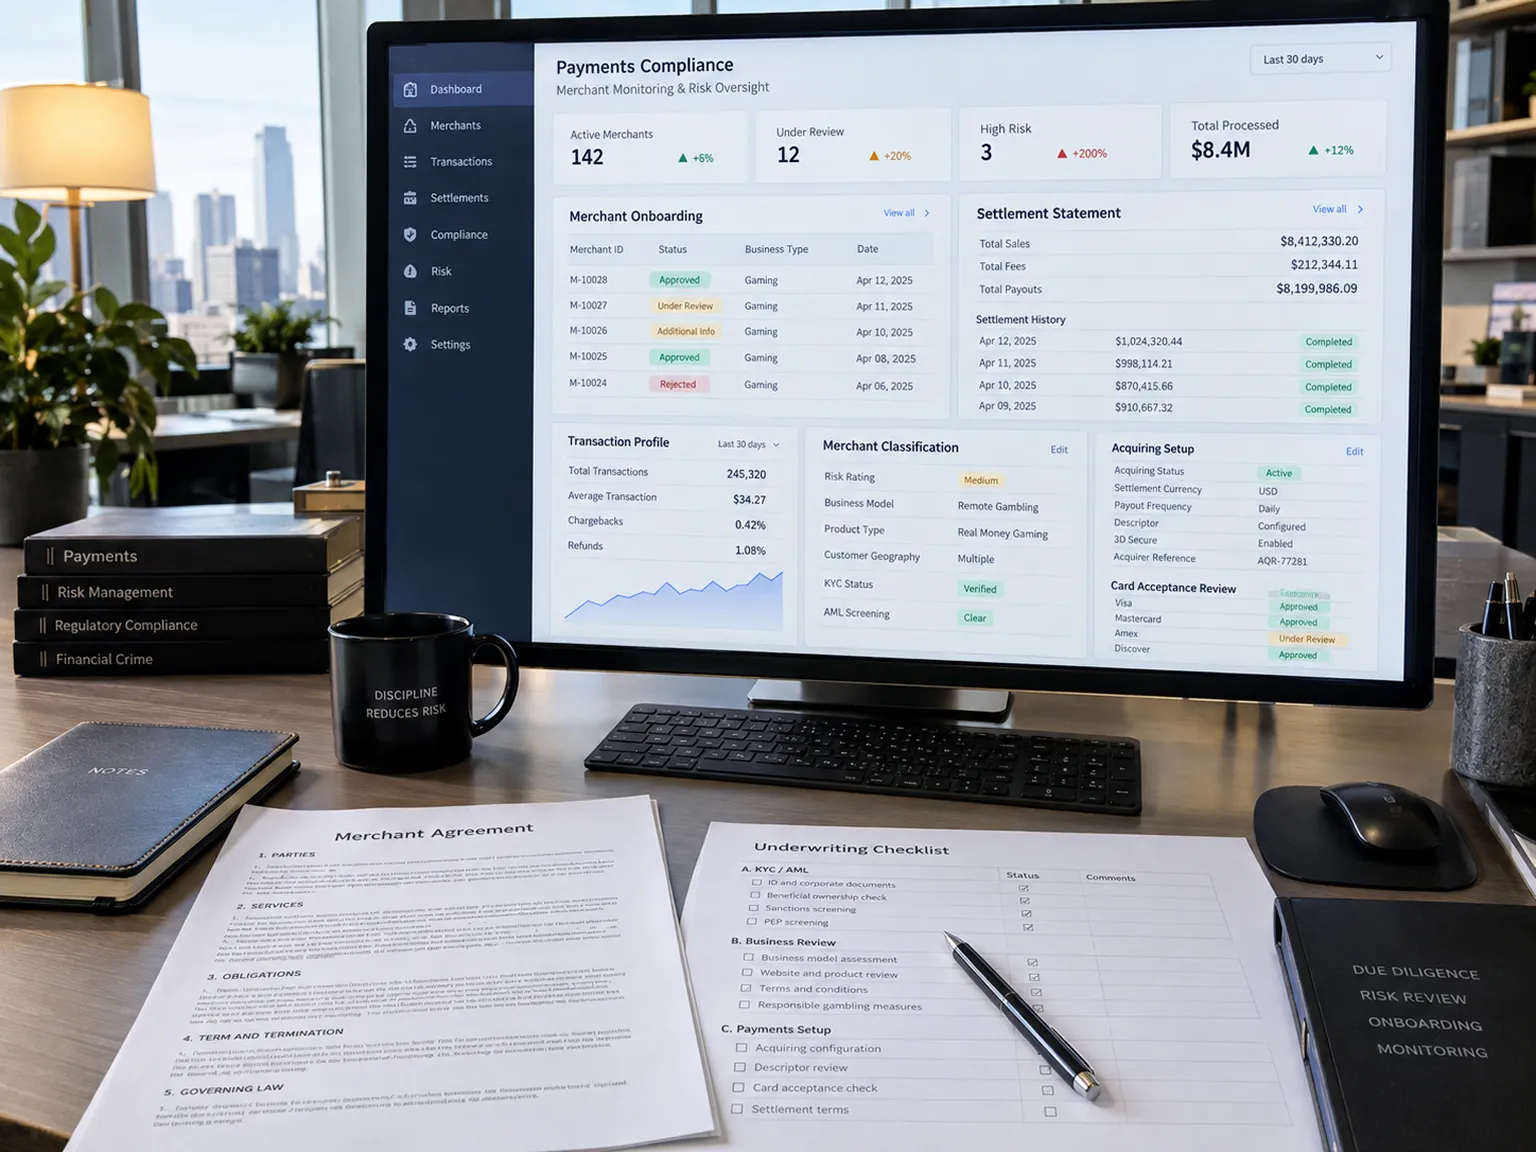
This guide explains what MCC 7995 covers, how it differs from U.S.-region gambling codes such as MCC 7800, 7801, and 7802, and what operators should check after an acquiring or authorization decline. MCC 7995 covers betting establishments and games of chance with prizes of monetary value. For card-absent Visa transactions, MCC 7995 is treated as a High Integrity Risk category, which brings additional acquiring controls. Qualifying U.S. lottery and gambling merchants must instead use the applicable MCC 7800, 7801, or 7802 (Visa).

Everything below follows the order an operator actually needs it in: what the code means, who it covers, how it compares to MCC 7801 and its other neighbors, why it triggers transaction declines and acquiring rejections, what it costs, how to check your own classification, and, if you’ve already faced either one, exactly what to do next.

What Is MCC 7995?

Short answer: Visa’s April 2026 Merchant Data Standards Manual defines MCC 7995 as “Betting, including Lottery Tickets, Casino Gaming Chips, Off-Track Betting, Wagers at Race Tracks and games of chance to win prizes of monetary value”. ISO 18245:2023 defines the broader merchant-category-code framework used to classify businesses (ISO). Under Visa rules, online gambling transactions generally use MCC 7995, while qualifying U.S. merchants must use MCC 7800, 7801, or 7802.

What a Gambling MCC Code Actually Controls

An MCC forms part of the merchant data attached to card transactions. It can affect issuer authorization policies, card-network risk requirements, and acquiring decisions. The code does not by itself determine one universal approval rate, interchange rate, or reserve requirement. Those depend on the issuer, acquirer, and merchant relationship behind it.
Two terms recur throughout this guide and they are not interchangeable. A transaction decline is a single payment rejected by the card-issuing bank — it’s about one authorization attempt. An acquiring rejection (or account termination) is the merchant’s own application or account being turned down or shut off by the acquirer supporting it — it’s about the merchant relationship itself. The fixes for each are different, and the sections below flag which one they’re addressing.

Who Falls Under MCC 7995 and Who Doesn't

Short answer: MCC 7995 generally applies to betting establishments and games of chance that offer prizes of monetary value. It is not the correct code for every real-money gaming product. Visa uses separate U.S.-region codes for qualifying government-owned lotteries, government-licensed online casinos, and government-licensed horse or dog racing, and certain card-absent skilled-game wagering can instead fall under MCC 5816.

Businesses That Fall Under MCC 7995

Businesses That Usually Don't

The boundary depends on the payment network, product structure, and jurisdiction. Visa can classify certain card-absent skilled-game wagering, including some fantasy-sports activity, under MCC 5816 rather than MCC 7995. Operators should confirm the applicable code with the acquirer instead of inferring it from product naming alone.

MCC 7995 vs MCC 7801 and Neighboring Codes

Short answer: for a US-facing operator, the MCC 7995 vs MCC 7801 distinction is the single most consequential classification decision in the entire payment stack. For Visa in the U.S. Region, merchants that qualify for MCC 7801 must use that code for online gambling transactions, rather than the general MCC 7995.
Code Covers Visa classification / note
7995 Betting establishments and games of chance with monetary prizes General gambling MCC; card-absent transactions fall within Visa's High Integrity Risk framework
7800 Government-owned lotteries U.S. Region only; merchant must meet Visa requirements
7801 Government-licensed online casinos U.S. Region only; merchant must be licensed or otherwise regulated by a U.S. government entity and registered with Visa
7802 Government-licensed horse or dog racing U.S. Region only; covers qualifying on- and off-track wagering
5816 Digital goods, games Can apply to certain card-absent skilled-game wagering
7994 Video game arcades / establishments Can include social casinos with no monetary prizes

Why 7995 vs 7801 Matters So Much in the US

MCC 7801 applies to merchants licensed by a U.S. government entity, or otherwise sanctioned and regulated by applicable legislation, and registered with Visa. A merchant should not switch between MCC 7995 and 7801 merely to seek higher approval rates. Authorization and pricing still depend on the issuer, acquirer, merchant profile, and transaction context, not on the code alone.

Why MCC 7995 Leads to Acquirer Controls and Issuer Declines
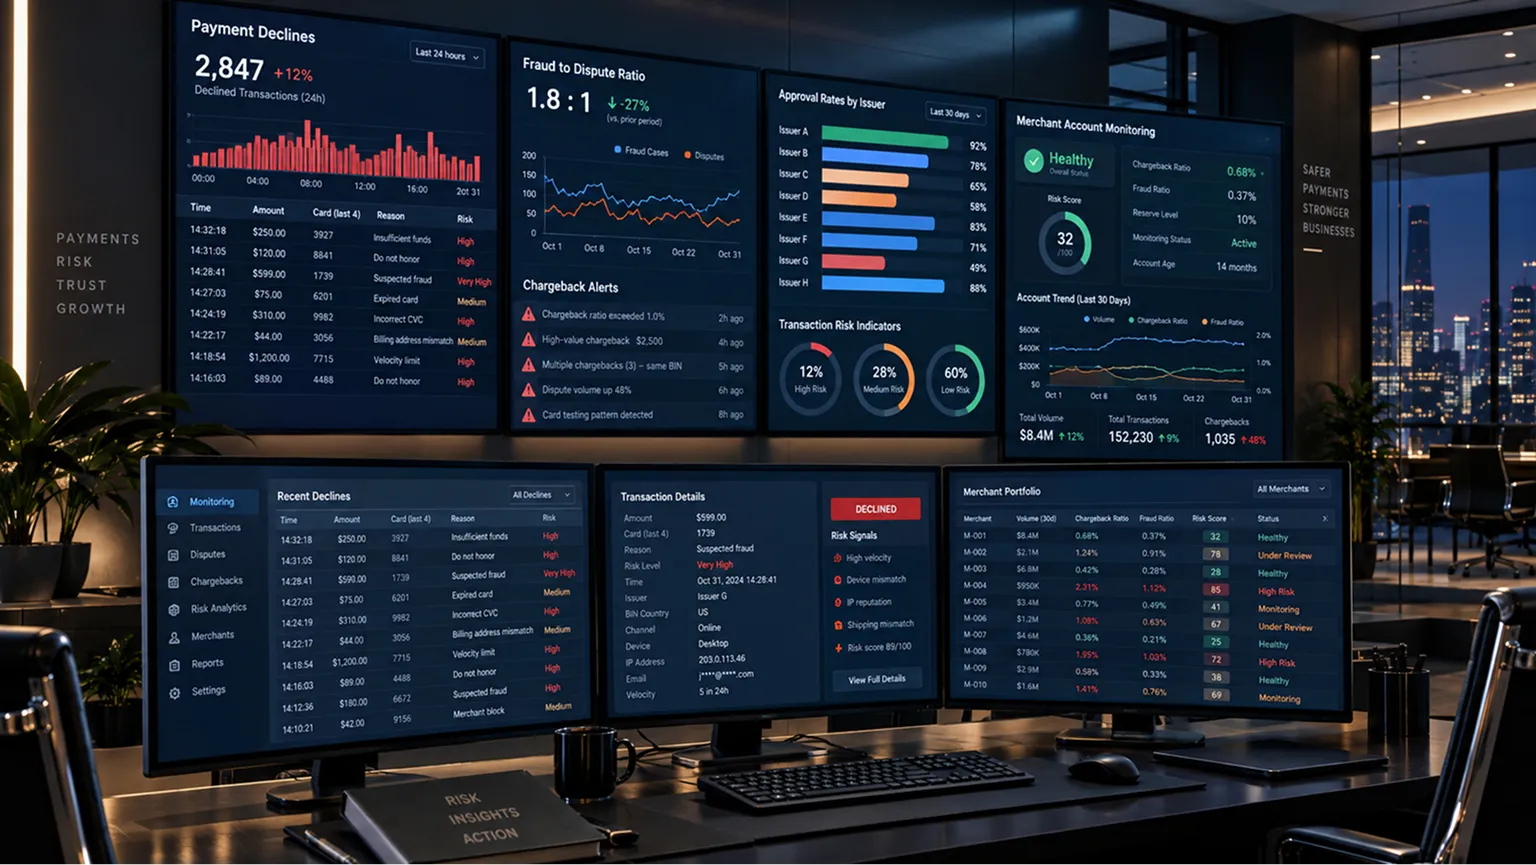
Short answer: MCC 7995 triggers two different things, not one. At the merchant-account level, Visa identifies card-absent gambling transactions in this category as High Integrity Risk, so the acquirer supporting that merchant must apply enhanced due diligence and ongoing monitoring — that’s about the account, not any single payment. At the transaction level, issuers can separately apply their own gambling policies, so authorization outcomes vary by issuer, market, card type, and merchant profile. MCC 7995 does not automatically signal a decline on its own.

Visa Integrity Risk Program Requirements

This is a merchant-account-level control, not a single-transaction decline. Visa’s Integrity Risk Program (VIRP) sets additional controls for High Integrity Risk merchants. Visa’s Acceptance Risk Standards require acquirers supporting these merchants to apply enhanced due diligence, and acquirers registering for Tier 1 High Integrity Risk acquiring must complete a control assessment for the approved category, with periodic reassessment thereafter (Visa).

Issuer-Level Blocks

This is where individual transaction declines actually come from. Beyond the network’s own program, individual issuing banks layer on blanket policies that have nothing to do with an individual merchant’s track record. Issuers can restrict gambling transactions based on jurisdiction, card type, internal risk policy, or applicable regulation. These issuer decisions are separate from VIRP requirements on the acquiring side. MCC 7995 can influence authorization logic, but the classification does not guarantee a decline.

The Economics of MCC 7995

Short answer: MCC 7995 does not impose one universal processing price. Gambling merchants can face higher acquiring costs, reserves, or monitoring requirements because commercial terms reflect licensing, geography, fraud and dispute history, volume, and acquirer risk appetite.

Interchange and MDR

Gambling merchants often face higher blended processing costs than standard e-commerce merchants because acquirers price in underwriting, monitoring, chargeback exposure, and scheme-related risk controls. Exact MDR and reserve terms depend on license, geography, processing history, chargeback ratio, and acquirer appetite.

Rolling Reserves

Visa does not publish a universal rolling-reserve percentage or hold period for MCC 7995 merchants — reserve terms are contractual and merchant-specific. For how reserve percentages, hold periods, and release schedules are typically structured, see our casino payment gateway guide.

Chargeback Fees and the VAMP Threshold

The Visa Acquirer Monitoring Program (VAMP) became effective on 1 April 2025 and combines reported fraud and disputes into one merchant-level ratio. Latin America and the Caribbean has applied a 150-basis-point (1.5%) Excessive Merchant threshold since 1 June 2025. Asia Pacific, Canada, the EU, and the U.S. started at a higher 220-basis-point (2.2%) threshold from that same date, stepping down to align with LAC at 150 basis points (1.5%) from 1 April 2026. Both thresholds also require at least 1,500 monthly fraud and dispute events; a merchant below that count isn’t measured against the ratio regardless of percentage. The ratio is calculated from reported fraud plus disputes divided by settled transactions (Visa).
Processing fees, rolling reserves, and contractual chargeback charges are set through acquiring and provider agreements. They are not universal Visa prices attached to MCC 7995. A specialist acquirer may be better equipped to underwrite gambling merchants and manage VIRP controls, but operators should compare written commercial terms rather than assume better pricing.

BillBlend states that it provides chargeback-management and high-risk payment services for gambling operators. Operators should confirm the acquiring entity, VIRP registration path, reserve terms, PCI scope, and chargeback conditions in the merchant agreement before processing begins. Get a free consultation to review your current setup.

Do you have any more questions?

Fill out the form, and we will contact you

*By submitting this application, you consent to the processing of your personal data in accordance with the privacy policy.

MCC Miscoding and How to Check Your Assigned Code

Short answer: using more than one MCC is not automatically a card-network violation. Visa can require different MCCs for distinct lines of business within the same operation. The compliance risk arises when gambling transactions are deliberately submitted under an incorrect, lower-risk MCC to evade classification or network controls.

The Mixed-Account Trap

Deliberately submitting gambling transactions under a general retail or recreation MCC (such as 7999) to avoid VIRP controls can violate card-network rules. Visa rules address altered or inaccurate merchant data used to circumvent risk-monitoring programs, and non-compliance can lead to assessments, remediation requirements, or restrictions, depending on the circumstances.

How to Verify Your Assigned MCC

Declined Because of MCC 7995? Here's What to Do

Short answer: “declined” covers two different situations here, and they need different fixes. A transaction decline is a single payment rejected by the issuer, usually fixable without changing acquiring relationships. An acquiring rejection or account termination is the merchant’s own application or account being rejected by an acquirer, which needs the full path below. Step 1 helps you tell which one you’re facing; steps 2 through 8 cover the acquiring-rejection path, from rejection to a new, working acquiring relationship.
  1. Get the real decline reason and confirm which scenario you’re in. “Declined” isn’t a reason; ask the current processor or acquirer for the specific issuer response code, in writing. A soft decline (insufficient funds, 3DS failure) is a transaction-level issue; fix it through retry logic, updated card details, or authentication tuning, not through the steps below. A hard block tied to the MCC itself, or an acquiring rejection or account termination, means steps 2 through 8 apply to you.
  2. Confirm your currently assigned MCC. Check the merchant agreement or a recent settlement statement to see what code is actually on file; don’t assume.
  3. Gather three to six months of recent processing statements showing approval rates, dispute history, reserves, transaction volume, and any prior termination information.
  4. Confirm whether the account was mixed-MCC. If gambling volume was coded as something else, disclose that upfront rather than letting a new acquirer discover it during underwriting.
  5. Assemble KYB and AML documentation in advance — a gambling license, beneficial ownership structure, AML policy, and source-of-funds evidence — so the new relationship starts with a complete file.
  6. Shortlist and vet providers using the acquirer-selection questions in our casino payment gateway guide — acquiring relationship, registration path, reserve terms in writing.
  7. Apply with the complete file assembled in steps 2 through 5, rather than piecemeal — applications move faster with everything ready upfront.
  8. In parallel, start diversifying into non-card payment rails where they are legal and commercially useful. Transactions that do not use Visa card rails are not part of VAMP calculations for those transactions, though each alternative method has its own dispute and compliance rules (more on this below).
Most of this can happen in parallel rather than strictly in sequence. The goal is walking into a new acquiring relationship with a complete file, not piecing it together after a second decline.

Regional Compliance Differences

Short answer: MCC classification and gambling compliance move together but aren’t identical. A license that makes an operator legal in a market doesn’t automatically improve the MCC treatment of its card transactions there.

In the U.S. Region, MCC 7801 applies only to qualifying online casino merchants that are licensed by a U.S. government entity, or otherwise sanctioned and regulated by applicable legislation, and registered with Visa. A state or other government gambling license alone should not be treated as automatic proof that MCC 7801 applies. In Great Britain, Gambling Commission Licence Condition 6.1.2 prohibits covered licensees from accepting credit-card payments for gambling; the restriction is a gambling rule rather than an MCC rule (Gambling Commission). In the European Economic Area, PSD2 strong customer authentication applies to relevant electronic payment transactions, subject to applicable rules and exemptions, while gambling licensing remains a separate national issue (EUR-Lex). Brazil’s regulated fixed-odds betting regime prohibits deposits by credit card and virtual assets; permitted funding uses approved electronic transfer methods such as Pix, TED, debit cards, or prepaid cards (Ministério da Fazenda).

Reducing Card Dependency: How Non-Card Rails Affect VAMP Exposure
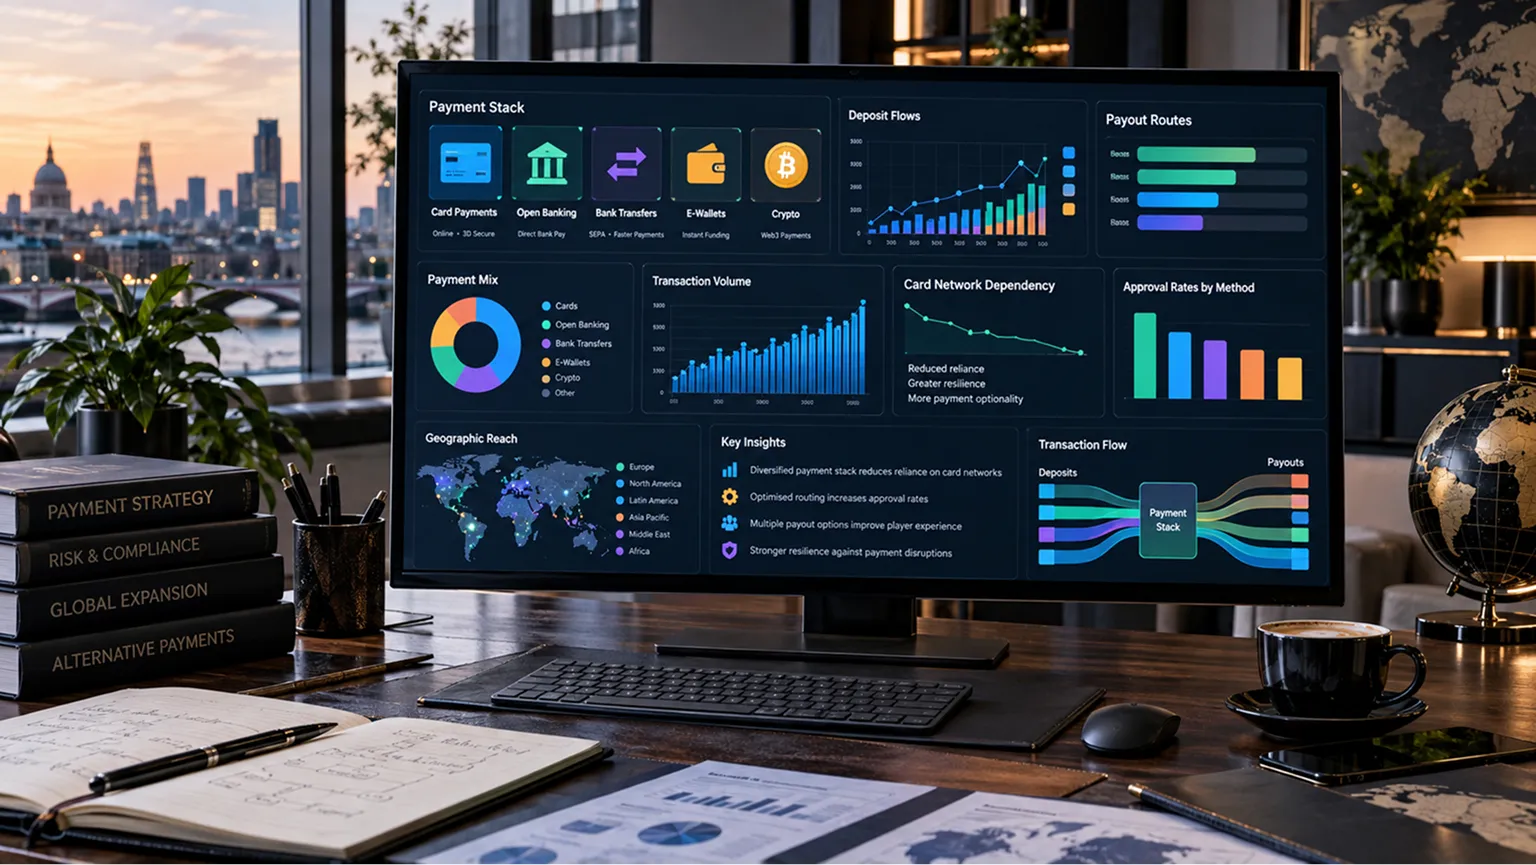
Short answer: the most durable fix for MCC 7995’s approval problems isn’t finding a better card acquirer; it’s needing fewer card approvals in the first place.

Direct bank payments, non-card-funded wallet transactions, and crypto transactions that don’t use Visa card rails aren’t Visa card transactions for VAMP purposes, which can reduce the share of deposit volume exposed to issuer card declines and Visa dispute metrics. E-wallets can still involve card-funded transactions, and alternative payment providers have their own compliance and dispute rules. For a full breakdown of these payment methods and how to structure a payment stack around this mix, see our iGaming payment gateway guide; our betting payment methods guide breaks down the individual rails from the player’s side.

At a glance, here’s how each rail is treated for VAMP purposes and how disputes work on it:
Rail VAMP / card-network exposure Dispute mechanism
Card Counts toward the VAMP fraud-and-dispute ratio Chargeback via the issuer
Open banking / bank transfer Not a Visa card transaction for VAMP purposes No card chargeback; refund and dispute rules depend on the provider and applicable regulation
Crypto (non-card-funded) Not a Visa card transaction for VAMP purposes No chargeback mechanism; on-chain transactions are generally irreversible

Why Operators Choose BillBlend for Gambling MCC 7995 Merchants

BillBlend positions itself as a high-risk payment partner for gaming and betting operators, with chargeback-management tools, fraud controls, and support built for High Integrity Risk merchants. BillBlend also states that its infrastructure follows PCI DSS requirements.

See how BillBlend's payment gateway for online gambling handles MCC 7995 registration and onboarding, or book a free consultation to review a recent decline and get a concrete next step.
Frequently Asked Questions

What is MCC 7995?
MCC 7995 is the merchant category code for “Betting, including Lottery Tickets, Casino Gaming Chips, Off-Track Betting, Wagers at Race Tracks and games of chance to win prizes of monetary value” under Visa’s Merchant Data Standards Manual. It’s assigned to real-money gambling merchants, and for card-absent transactions, Visa treats it as a High Integrity Risk category, which brings additional acquiring controls and can mean higher scrutiny and processing costs than standard categories.
MCC 7801 applies to government-licensed online casino merchants in the U.S. Region that are registered with Visa; merchants that qualify for it must use it instead of the general gambling code. MCC 7995 is the broader classification for betting and games of chance elsewhere. Neither code alone determines approval rates or pricing; that still depends on the issuer, acquirer, and merchant relationship.
Individual transactions get declined by the card-issuing bank, based on its own gambling policy — jurisdiction, card type, or internal risk rules, regardless of the merchant’s track record. That’s separate from Visa’s Integrity Risk Program, which requires the acquirer supporting a High Integrity Risk merchant to run enhanced due diligence and monitoring on the merchant account itself, not on individual transactions. Some markets also restrict specific instruments outright, such as the UK Gambling Commission’s ban on credit-card payments for gambling under Licence Condition 6.1.2.
First establish which one happened: a single transaction declined by the issuer is a transaction-level issue, fixable through retry logic or authentication tuning, not an acquiring problem. If it’s your merchant application or account being rejected or terminated by an acquirer, get the exact reason in writing, pull recent processing statements, and take both to a specialist that can explain how its acquiring bank supports High Integrity Risk merchants. Prepare KYB and AML documentation in advance, and consider shifting some deposit volume to open banking, e-wallets, or crypto rails that fall outside Visa card-transaction reporting.
Check the merchant agreement, onboarding paperwork, processor dashboard, or a recent settlement statement (most acquirers display the MCC there), or ask your acquiring bank to confirm it in writing.
Real-money gambling activity has to be coded as gambling. Deliberately submitting gambling transactions under an inaccurate lower-risk MCC is MCC miscoding and may constitute transaction laundering or a breach of card-network rules. The workable strategy is accurate coding paired with a specialist acquirer and less reliance on cards overall, not avoiding the code.
1
0

Do you have any more questions?

Fill out the form and we will contact you

*By submitting this application, you consent to the processing of your personal data in accordance with the privacy policy.

Did you like the post? You can share it!

Did you like the post?
You can share it!

Programmer and developer with over 20 years of experience.

Author's assessment

Leave a comment:

Table of Contents

Other publications

Answer 5 questions and find out the cost

By clicking on the button, you agree to the data protection policy

Contact us

By clicking on the button, you agree to the data protection policy

Complete the quiz

By clicking on the button, you agree to the data protection policy